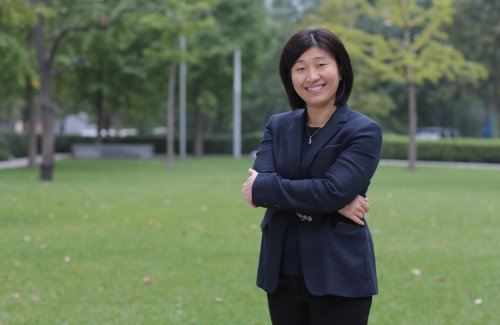
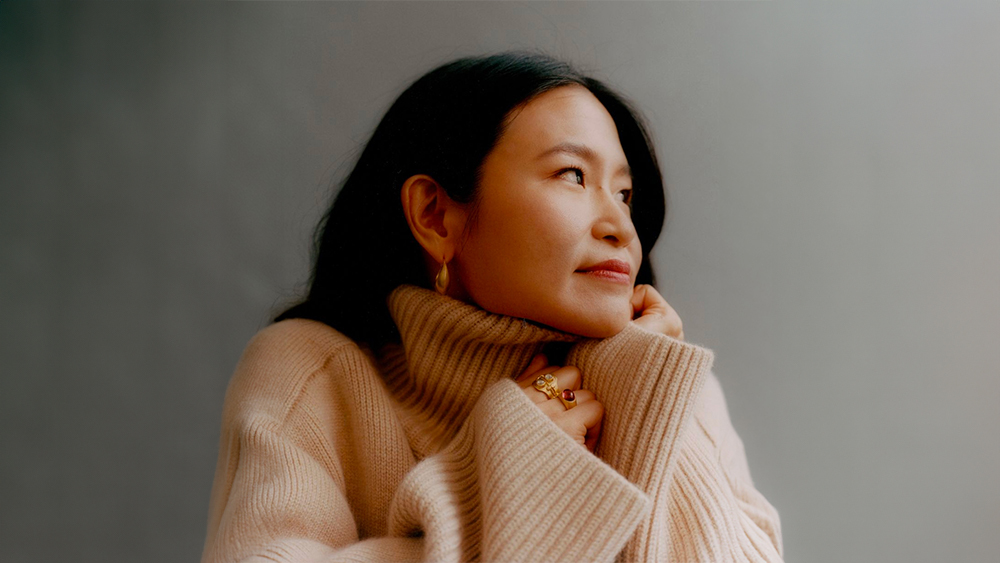
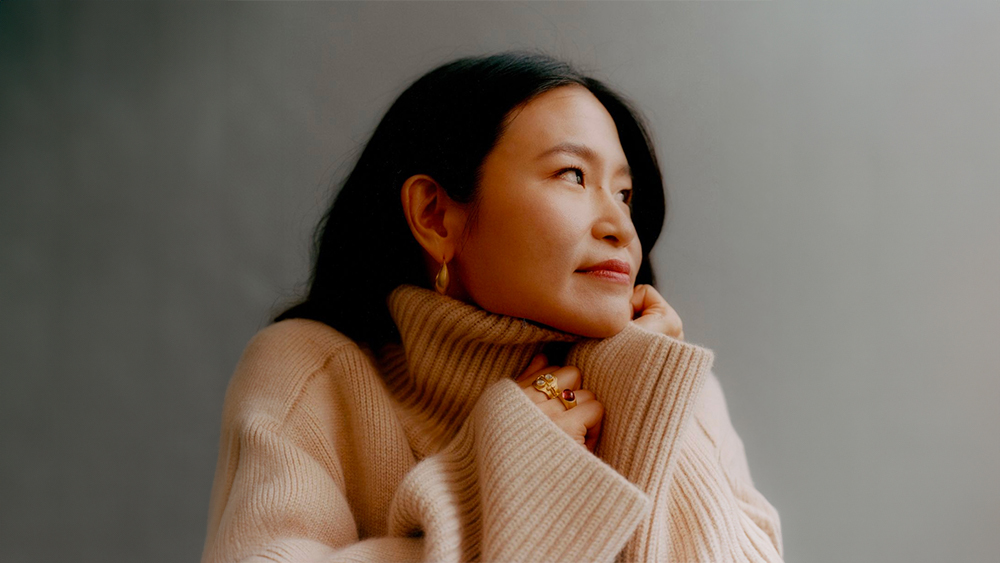
Venture capitalist Ann Lai is, by all measures, an absolute beast. From earning a PhD from Harvard at 25 to becoming Managing Director at her own firm–Skeleton Key, Ann has clearly achieved a great deal of success throughout her career. Ann is also notable for speaking up publicly about the misogyny she has faced in VC, despite it nearly forcing her out of the industry. I had the honor to chat with Ann about her career journey pre-VC, reflections on her identity, and also about her exciting new firm.
Journey to Venture Capital
Ann’s journey to Venture Capital is at least 50x cooler than mine. In fact, it’s one of the coolest there is. It all started when she read a biography of Marie Curie at the age of six. I asked Ann to explain what drew her to Marie Curie so much that it set her on a trajectory she is still on today:
The recognition of women in science has historically been insufficient, and I have consistently been attracted to narratives that feature an underdog. Marie Curie’s achievement as the first woman to win a Nobel Prize, and then winning it a second time, was profoundly significant to me as a young person. From a very young age, I had an affinity for science and engineering. My mother, a teacher of literature, encouraged me to read or listen to autobiographies of diverse individuals. My early fascination with NASA was spurred during the time my father worked there. Marie Curie significantly altered the landscape and methods of many scientific endeavors.
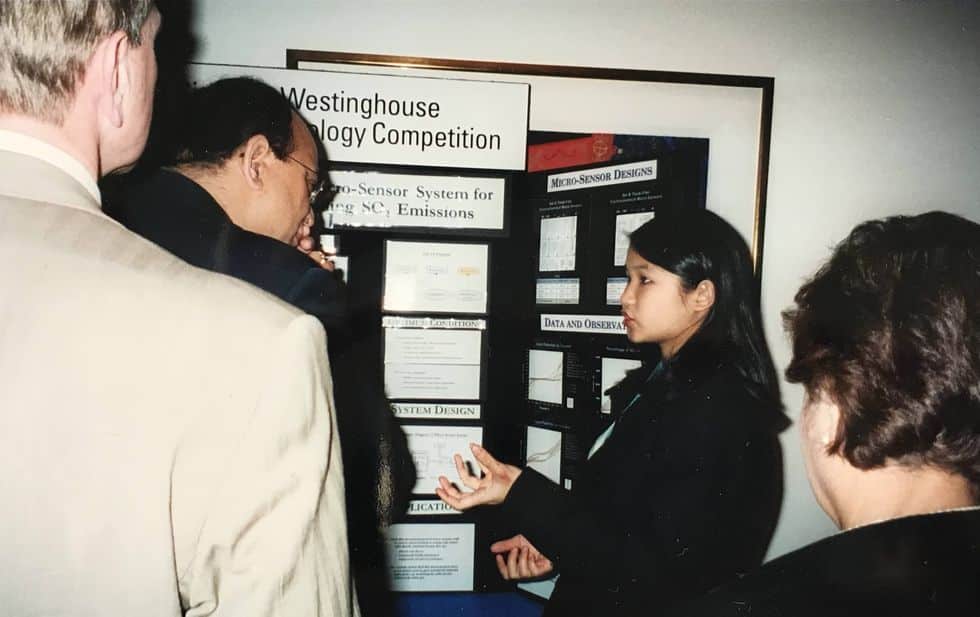
Marie Curie’s story inspired Ann to study science. By age 25, she had earned three STEM degrees from Harvard including a PhD in microfluidics. While studying, Ann was starting to notice things that would push her away from being a scientist towards investing:
I noticed that many significant scientific advancements were transitioning to privatization. There was a golden era of science in the United States during the 1970s, characterized by substantial government funding and innovative labs such as Xerox and Bell Labs, but it is now over. I hypothesized that the most groundbreaking scientific discoveries would increasingly be funded privately. The sectors that remained vibrant, like CRISPR and space exploration, were those receiving substantial private investment. And although I was satisfied in the laboratory, my broader interests and extroverted personality drew me toward the funding side of science.
However, that was not quite what the universe had in mind for Ann. Ann graduated right around the 2008 financial crisis, which had pretty much killed off all appetite for investments in science. Thus, she instead started her career at a firm pioneering big data analysis:
I joined a company on Wall Street that pioneered what is now commonly referred to as “alt data”. We acquired, scraped, and sourced new and proprietary datasets, transforming them into predictive models for public company earnings. This was a rigorous introduction to the underlying forces that influence corporate dynamics; we had to understand the key performance indicators driving stock market values. (It was like going through a condensed MBA program.) By modeling quarterly earnings, where data points were scarce, I applied methodologies from my graduate research, collapsing extensive data sets by normalizing or parameterizing the variables, allowing for a comprehensive, dynamic model. This approach was highly effective, blending scientific and business analytics.
After her stint working in finance, Ann went on to lead business intelligence for international territories at Riot Games and then worked in a few early-stage startups in preparation for a transition into Venture. One thing she said especially caught my attention:
There was noticeable skepticism towards PhDs and academics in venture capital. Despite my extensive scientific background, I was told to strategically minimize the emphasis on my PhD on my resume. It’s evident in the venture space that there is a prevailing belief that academics lack practical business acumen.
When asked whether this skepticism extended to PhD founders, Ann elaborated:
This skepticism is indeed still prevalent. However, many PhDs are exceptionally practical. For companies involved in iterative development, such as SaaS companies, the requirements are different. In these fields, the emphasis is more on user interaction and less on deep scientific knowledge. But, for science-driven enterprises, a thorough understanding of the fundamental sciences is crucial.
Hopefully, this gives some hope to the PhDs out there who are looking to start a company! In fact, VC has been trending more towards deep tech evidenced by an increased share of investments into the space.
Advice for Women in Venture
One aspect Ann has been noted for is her outspokenness on the misogyny she has faced in the Venture ecosystem. For more specifics about her experiences, you can check out this Elle article written about her. Given her experiences, I asked her what advice she would give to women who want to go into the VC or startup space, but are concerned about the misogyny and fraternity culture that is still rampant.
Establishing a close network of mentors and peers for support is essential. This has been invaluable to me. Unfortunately, the prevailing culture remains challenging, and the progress we’ve made has perhaps deteriorated in the past year due to decreased venture capital availability on the LP side. There’s still a lot of work to do. The solidarity of women supporting one another is crucial for fostering progress. Maintaining a commitment to support each other is critical. Although most days it may not seem particularly difficult, there are specific moments where you can just feel a very big demographic difference in terms of who’s empowered. Partners are partners, but managing partners are different categories of partners. Until more women are managing partners or running their own sizable firms as partners, there’s still not enough leverage in the space.
Being Asian
I asked Ann to reflect on how her identity as an Asian woman has affected her lived experience:
My mother is incredibly liberal for her generation of Taiwanese. She has always been supportive, telling me I don’t need to get married early or worry about having kids, which is rare for Asian moms of her generation. At the same time, my parents weren’t financially very well off when we came back to the States. I contributed to my family’s income from the age of 12. There was no safety net. If I didn’t make it, nobody could pay the bills. It taught me resilience and gave me a “no way back” approach to life.
My dad raised me with a strong sense of right and wrong (We watched a lot of Asian martial arts dramas and stories.) It’s not really about being visible–it’s about doing the right thing. This Asian heroism as defined by martial arts movies approach is quite different from American heroism, and it’s the reason why I stood up for myself even when it might have prevented me from working again.
Being an Asian woman in the US is difficult. I often get the assumption that I’m a lot younger, for example. So, you always have to go into a meeting fighting that. That’s something my cohort and I have talked about a lot, like, you learn how to dress and style yourself to appear older sometimes so that you will be taken more seriously.
For meetings in East Asia, I was coached to open meetings by stating my qualifications, the PhD from Harvard, etc.This way, they respect the degree and then they respect you. Male executives and men who attend meetings weren’t prepped in this way. But I’m starting to see more evolution, especially with the younger, successful Asian male founders and groups. They’re very supportive, which is great. The older generations still tend to have a more patriarchal mindset, but it’s getting better, especially in the US.
Anecdotally, children of first-generation immigrants often pursue more stable, high-paying careers (doctor, lawyer, etc.), yet Ann has clearly bucked this trend. I asked her why she thought she ended up doing so:
My parents have been very modern in their thinking. They’ve never said I had to do things in a certain way. They’ve always supported my decisions. It made me feel like I could do anything. I’ve never worried that I might not succeed. If you are fearless, you end up doing aggressive things, aggressive in a good way.
Having grown up in both the US and Taiwan, I think Western and Eastern education are quite different. The American system encourages exploration and aspirations, whereas there’s a lot more regimen in the Eastern education system. The way I was raised was very much a marriage of those two aspects in an unexpected way. I have a lot of friends who were told to be a doctor or a lawyer, but if you think you can do better at other things, why do you have to do that?
Skeleton Key
A Skeleton Key is a type of master key in which the serrated edge has been removed in such a way that it can open numerous locks. It is also the name of Ann’s new firm. While researching for this interview, I came across this article by Ann, where she lays out the argument for why Deep Tech is venture-backable. Towards the end of the article, she shifts the focus to ScienceTech (SciTech), which she defines as: the software, platforms, or tech-enabled services that accelerate scientific discovery or assist in bringing science to life. I asked Ann why she chose Skeleton Key’s focus to be on SciTech instead of Deep Tech:
Deep tech is definitely fundable, as I’ve talked about. But now with AI, I’m thinking about how to make deep tech happen faster. Instead of investing in a drug, I’m looking at the platforms helping people discover drugs faster. Those layers are interesting to me, and I think those are the layers where a lot of the accelerated computing power can come into fruition in an interesting way. The accelerated computing power means you can map out a lot of things that have historically been very difficult such as fatigued glass behavior or certain thermal dynamics, nonlinear dynamics, and anything that’s related to nonlinear systems.
There’s even a lot of interesting stuff happening around the application layer of science. For instance, bringing chemicals to real-life applications usually takes a long time. You find a chemical and wonder where to use it and what it can be used for. Then, usually, you need a different type of manufacturing protocol or a different variation for each use case. But now, you can find a lot of those variants much faster. The formulation or the tuning of that molecule, protein, etc. can be assisted on by AI and you accelerate that process of bringing it to a real-life application much faster.
As you may have gathered from her background, one of Ann’s specialties is data analysis. In her previous VC roles, Ann leveraged her background to evaluate companies based on their data in an apples-to-apples way. You can hear more about her approach in this podcast. Given that Skeleton Key is working with a type of company that isn’t what the typical VC invests in, I was curious to know if she had to adapt her process:
It’s definitely different for Skeleton Key. We deal with a lot more data around R&D and early applications because we’re focusing on a second or third institutional round for these folks–so it’s a post- R&D but before they actually hit ramping revenue. That means you still have time to work with them on exploring the business–is it a software platform approach, or is it a single molecule approach, or a single robot approach?
I asked Ann what revenue the companies typically are at in their second or third institutional round:
I think the specific revenue number doesn’t really matter. It’s the mechanics of what the early performance looks like. If they have a couple of contracts which are scalable over time and show real adoption and real usage–that’s a lot more important than one marquee SaaS contract that you can get through relationships. It’s more around the usage, the actual day-to-day functionality or day-to-day use.
Earlier in our chat, Ann touched on how Skeleton Key plans to help startups explore different business angles, I asked Ann to elaborate on this process:
Our approach is very collaborative. My philosophy has always been to provide as much help as the founder wants. The goal post-investing is to help them with monetization, go-to-market strategies, and thinking about how to scale from a scientific lab mindset into building a company. We also assist them in fundraising. There are a lot of resources post-investment, and whether a founder will leverage them is their choice, but we prefer that they are open to us being more involved. In this category, where there are no established revenue models and many founders are coming from academic backgrounds, this advisory capacity is helpful to give them the full lay of the land, let them explore, and let them test different monetization hypotheses quickly. Inflexibility or lack of adaptability can be a problem down the line, especially in these categories that require a lot of money for ramping up and the revenue models aren’t so obvious. In fact, we’re planning on helping founders in this way before even investing, as part of our process.
I mentioned to Ann that this kind of help seems very valuable, especially since the only resources available online tend to be very reductive:
My biggest pet peeve is when VCs prescribe a framework without actually understanding the problem. When we help companies, we don’t do that. We workshop their unique situation and how to price best for their product, without capping future revenue. For example, a lot of people like to suggest ARR subscription SaaS, but that model doesn’t work for everyone. There’s a lot of possibilities around pricing and revenue that isn’t just about “getting ARR.” I think those are the interesting exercises to think through when you’re in these new categories.
Shoutouts
Ann is amazing and I am super excited for the launch of Skeleton Key. If you’d like to hear more from Ann, you can sign up for her Science Fair newsletter here, where she writes about science and venture. Thank you Ann for the great interview!