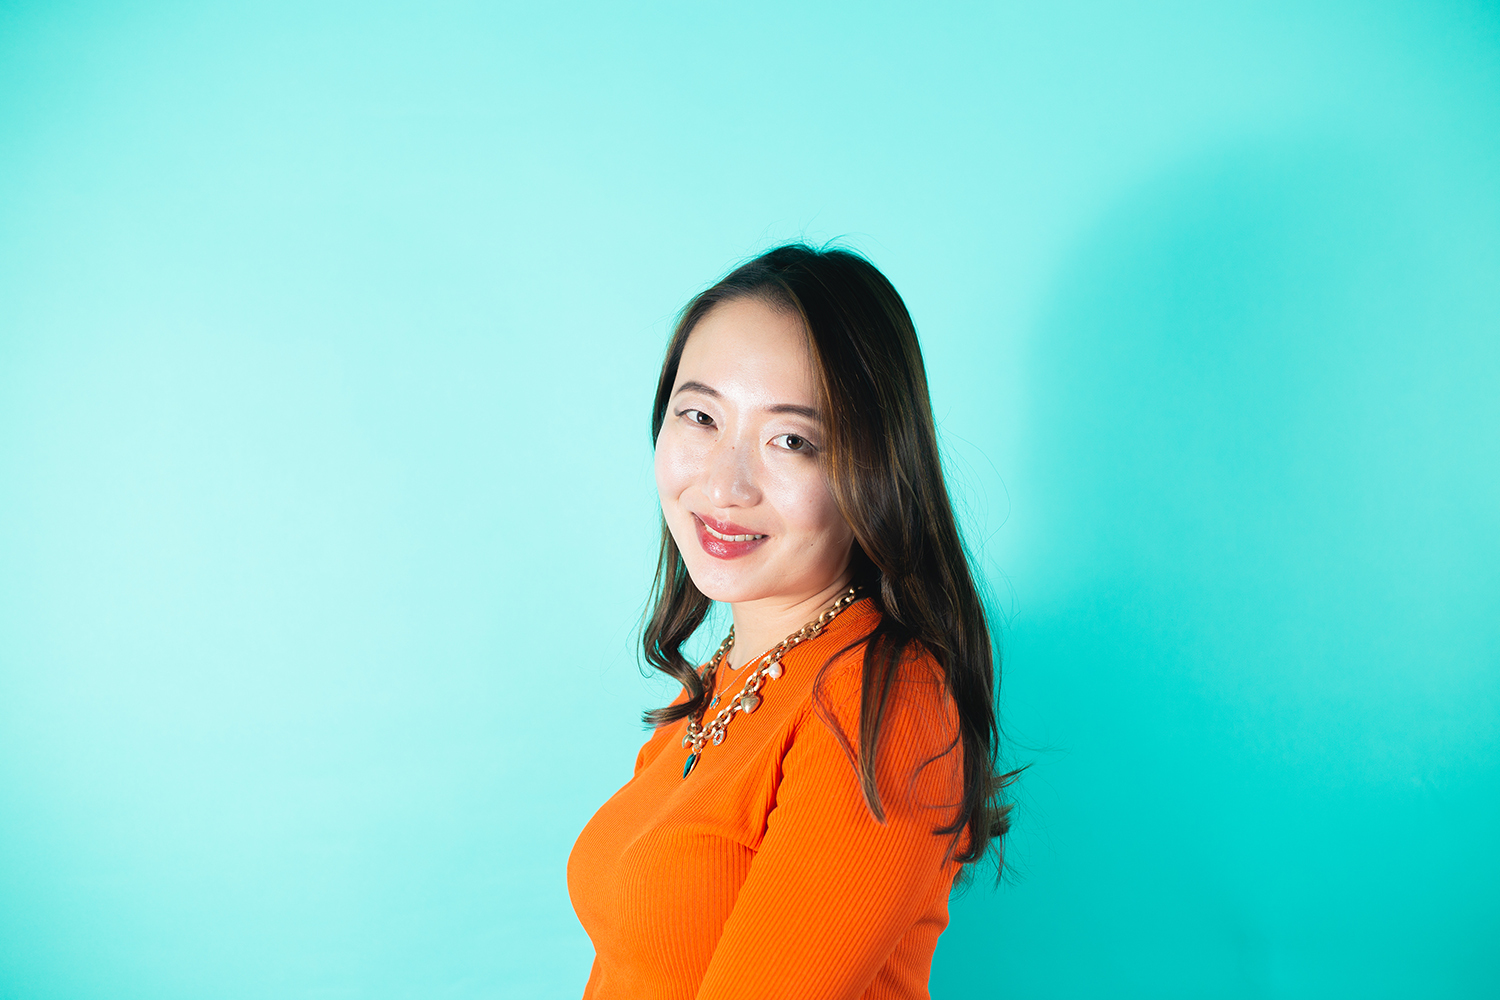
In this month’s edition of the Awaken* Newsletter, we speak with Kristy Kim, Founder and CEO of TomoCredit, a fintech startup focused on improving access to credit for underserved consumers. By using AI to evaluate real-time cash flow data rather than traditional credit scores, TomoCredit connects consumers with lenders.
Kristy discusses her journey as an immigrant, an Asian female founder, and an entrepreneur working to transform the financial industry. Through her leadership, TomoCredit aims to provide more people with better access to capital and lending opportunities.
Can you start by giving us an overview of your company and what you’re trying to solve?
Kristy Kim: Sure! At TomoCredit, our mission is to bridge the gap between underserved consumers and lenders using AI technology. We are focused on serving individuals who have been left behind by traditional financial systems, especially those without credit scores or with limited credit history.
There are millions of people in the U.S. who are underbanked, and the financial institutions that could potentially help them either don’t have access to their data or don’t understand their risk profile. We leverage AI to evaluate consumers based on their cash flow instead of relying solely on traditional credit scores. This enables us to match these individuals with lenders who are willing to serve them without taking on additional risk. Our platform helps both consumers and lenders—consumers get access to capital, and lenders expand their market in a low-risk way.
What motivated you to start TomoCredit?
As a first-generation immigrant from South Korea, I moved to the U.S. at eleven. In my early twenties, I faced the challenges of building my own credit history. After graduating from UC Berkeley, I worked in investment banking.
Despite having a stable income, I was denied an auto loan five times because I lacked a credit score. This experience highlighted a significant gap in the financial system, where many immigrants, young adults and many other underserved communities are excluded due to the absence of a credit history. After being turned down multiple times, I knew something had to change. I saw that the traditional credit system wasn’t serving millions of people, particularly immigrants, who had the ability to repay but lacked a credit history to prove it.
That experience of being excluded from the financial system really motivated me to find a way to help people like myself access the credit they needed. Determined to address this issue, I founded TomoCredit to provide credit solutions for those who, like me, struggle to access traditional credit avenues.
I wanted to create a system that didn’t rely on traditional credit scores but instead used alternative data, like cash flow, to assess creditworthiness. The idea was to connect underserved consumers to lenders in a way that wouldn’t increase their risk. TomoCredit was born out of this desire to make the financial system more inclusive—so others wouldn’t face the same rejections I did, and would have the chance to access capital and thrive.
As an immigrant founder, have you faced any challenges or biases in fundraising or building relationships with big institutions?
Kristy Kim: Yes, there are definitely challenges that come with being an immigrant founder, and at times, it can feel like an uphill battle. But, interestingly, my background has also played to my advantage.
As an immigrant, I have a unique lens on the problems facing underserved communities. I know firsthand what it’s like to struggle with the traditional credit system. I’ve faced the same barriers that many of our customers face, and that gives me an edge when I’m speaking to financial institutions. I’m able to say, “Look, I know my customers better than anyone else. These people are creditworthy, but they’re being overlooked by the traditional system.”
There is some bias, of course, especially when you’re dealing with legacy institutions, but I think they also recognize that I bring something different to the table—an intimate understanding of the market and the customers they often don’t have access to. Lenders are willing to listen because they know that by partnering with us, they can expand their pool of potential customers without taking on additional risk.
You’ve been in this industry for over five years now. What keeps you motivated despite the challenges you’ve faced?
Kristy Kim: That’s a great question. Honestly, the progress we’ve made keeps me motivated. Every year, I see the interest in our approach growing, and it reinforces that we’re heading in the right direction.
When we first started, it felt like I was an outsider trying to convince traditional financial institutions to embrace an entirely new way of evaluating credit. But now, year after year, we see more and more mainstream players realizing that there’s a huge market for underserved consumers—and that these consumers are creditworthy if we just use the right tools to understand them. It’s exciting to be at the forefront of this change.
For me, it’s not just about building a business—it’s about creating lasting impact. The U.S. consumer credit industry is worth over $4 trillion, and the fact that we are focusing on a largely ignored segment of that market feels like we’re making a real difference. And, of course, as a founder, seeing our technology evolve and improve with time and data is incredibly motivating.
How does your solution differ from other competitors in the market who are also targeting underserved consumers?
Kristy Kim: The key differentiator is that we don’t just rely on traditional credit scores to assess risk.
Our AI model is powered by cash flow data—essentially, we evaluate consumers based on their spending and income patterns, which gives a far more accurate picture of their financial health. Over the past five years, we’ve accumulated a wealth of data that allows us to refine our model, and with every new data point, we get better at underwriting.
Unlike competitors who may be using generic data or building from scratch, we have a more granular understanding of how underserved consumers behave financially. Additionally, the beauty of our system is that we’re not just looking at data from one financial institution—we’re aggregating data from multiple sources. Our customers might have accounts with multiple banks, and that gives us a fuller picture of their financial habits. In comparison, other companies might only have access to data from one bank, which limits their ability to assess risk accurately.
As a founder, what has been the most rewarding part of your journey so far, and what has been the hardest?
Kristy Kim: The most rewarding part has been seeing the validation from both the industry and our customers. When leaders of financial institutions tell me that TomoCredit makes sense, it’s incredibly validating. It’s a feeling of affirmation that, yes, we’re on the right path. But it’s also rewarding to see the real-world impact we’re having on people’s lives. We’ve helped thousands of people access capital who otherwise wouldn’t have had the chance.
On the flip side, the hardest part has been dealing with the mental burden of being a startup founder. When things are going well, it feels like everything is moving at full speed, but when challenges arise—whether it’s fundraising hurdles, market uncertainty, or hiring struggles—the pressure is immense. Unlike larger companies with more resources, startups have less margin for error. It can feel like one wrong move could jeopardize everything, and that can be emotionally exhausting. But it’s in those moments that you really find your resilience, and you learn that, no matter how tough it gets, you have to push forward.
As a seasoned founder, what key lessons from your previous startup experience have you applied to building TomoCredit?
When I launched my first company, I was in my early twenties, full of energy but lacking experience. It was a trial-and-error journey, where I learned a lot, but I quickly realized that having a clear vision and understanding the real impact you want to make is crucial.
Starting TomoCredit was a completely different experience. This time, I approached it with a clear strategy, having learned the importance of tackling a problem that I was personally passionate about. My previous startup experience taught me how to make more strategic decisions, prioritize what matters most, and stay resilient through the inevitable ups and downs of entrepreneurship.
What advice would you give to aspiring founders, particularly those who may be feeling discouraged after a tough year?
Kristy Kim: My advice would be to stay grounded in your purpose and conviction. It’s easy to get distracted by the ups and downs of the startup world, but at the end of the day, your mission should drive you more than the fear of failure or the setbacks you face along the way.
When I first started my company, it wasn’t about just building a business—it was about solving a real problem that I deeply cared about. The passion for the idea needs to be stronger than the fear of failure. Even if things don’t work out the way you hope, you can still be proud knowing that you tried to create something that could have made a real impact.
The most successful founders I know are the ones who are able to maintain a strong sense of purpose, even when it feels like everything is falling apart. If you believe in what you’re doing and are committed to the long-term vision, that will carry you through the hard times.
What are some recent key achievements or milestones that you’re excited to share?
Kristy Kim: Thanks for asking. First, our AI-driven platform continues to help underserved consumers access credit by using cash flow data to connect them with lenders.
We’ve also made significant strides in improving our underwriting capabilities by leveraging years of data to assess creditworthiness more accurately. This year, we paused issuing new credit cards to focus on refining our AI and underwriting technology. While we haven’t issued new cards yet, we’re still accepting customers and offering other financial services. Additionally, our partnerships with larger financial institutions are also growing, with increasing interest from major players. These collaborations are essential to our mission of expanding access to lending for underserved communities.
And lastly, on the team front, we’ve made several key hires, including the former CTO at Experian and the former CEO of LegalZoom. Their expertise in open banking and scaling high-growth companies will help us continue to expand our offerings and further our mission.
Looking ahead, what’s next for TomoCredit?
Kristy Kim: We’re expanding our offering, bringing more lenders into the network, and continuing to refine our AI technology to provide better risk assessments.
We’ve been growing the B2B side of our business over the last year, and we’re seeing significant interest from bigger players in the financial sector. We’re also planning to expand our product offerings to include more types of loans, like auto loans and mortgages, to help more customers get the access they need.
We’re also actively hiring, which is very exciting for us. We’re looking for a talented marketing person to help us build our brand and spread the word about what we’re doing. Our mission is to make financial access easier for everyone, and we’re excited to continue growing and impacting even more lives.
Kristy Kim’s journey proves that determination, a clear vision, and a deep understanding of your market can break through even the toughest barriers. At TomoCredit, she’s not just building a company; she’s seeking to reshape how credit is accessed, especially for those often left behind by traditional systems. Stay tuned for more updates on TomoCredit’s journey, and learn how they’re challenging the status quo while creating new opportunities for underserved communities.
Author: Donna Yu