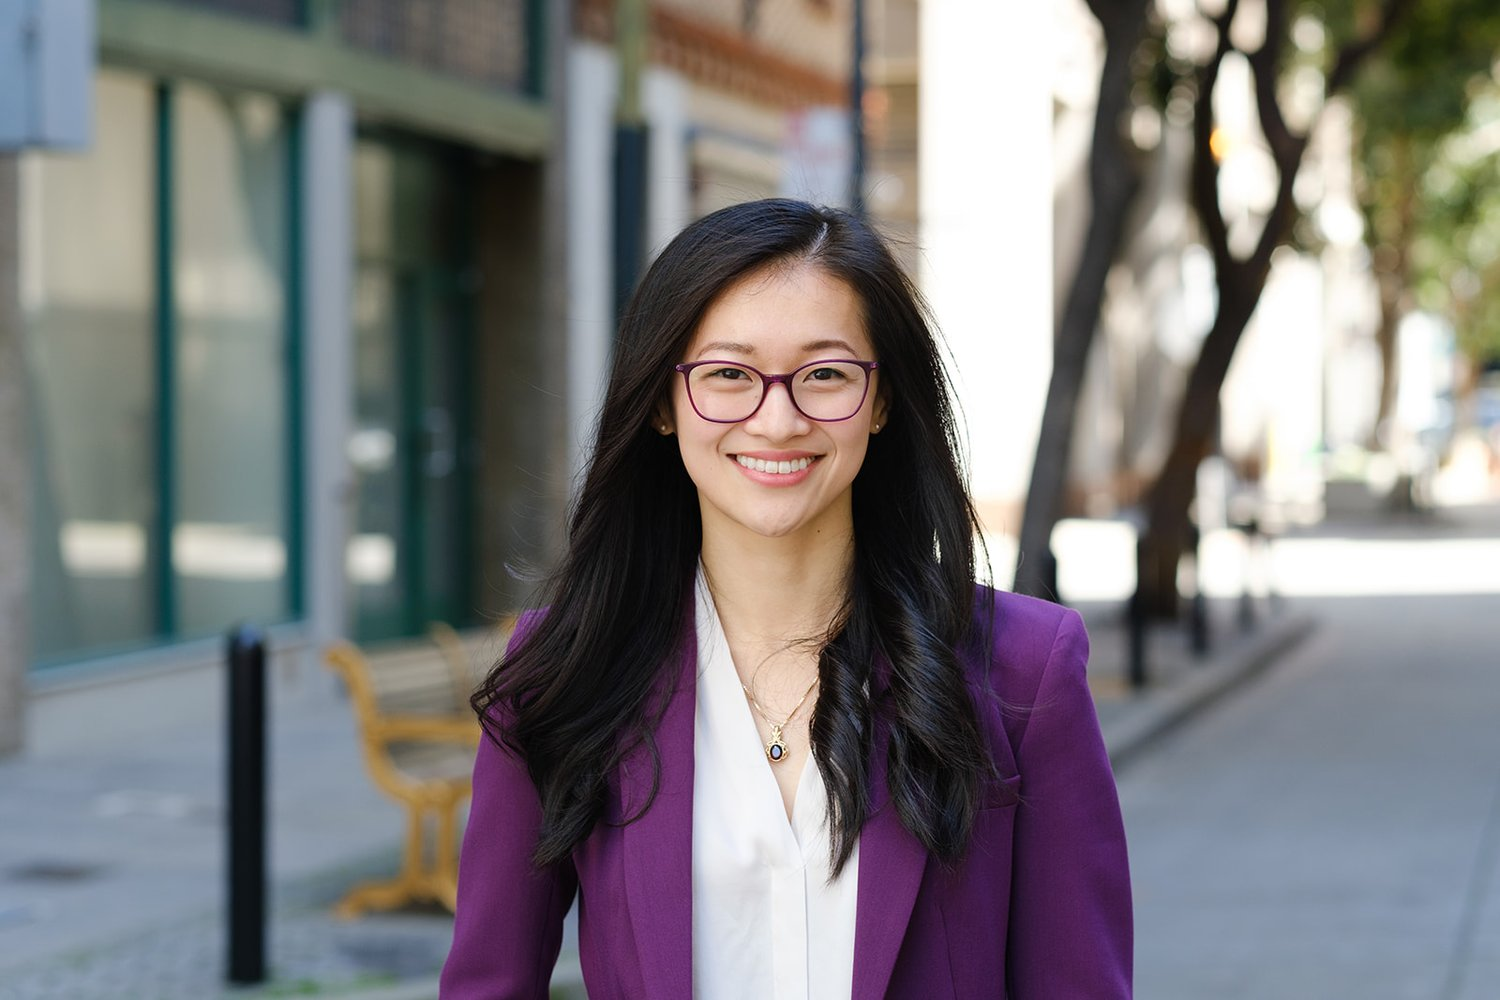
In the half-year I’ve been writing this newsletter I have only interviewed established founders. This article is my first deviation from the pattern and I couldn’t have asked for a better guest. Emily Luk–though a first-time founder–is not new to startups, having joined Stripe as a founding member of their growth team back when the company was around ~150 employees.
Now, she is building Plenty, an investment platform for modern couples. Talking to Emily has convinced me of two things, first–that this is a very large and important problem, second–that Emily is probably the right person to build it. I’m excited to share my conversation with her.
TLDR; Key Takeaways
If you only have a few moments, here are a few golden nuggets from my conversation with Emily:
- An exercise to find your calling: Write down everything that makes you happy, ~100 words. Keep cutting the list in half until you have five words. What’s the grounding/theme that goes through all five? That’s a good starting point to find your calling.
- Address opportunity costs before starting a company: Running a successful startup is a long journey, the average time to IPO is 7-10 years. If possible, do the things you’d regret missing out on before embarking on your journey.
- Aspiring founders should focus on developing taste: As a founder, you don’t need to do everything personally yourself, but you need to know what great looks like. Working alongside great talent can help you develop this intuition.
- Being relatable is a core part of business: People are much more likely to do business with you if they can relate to you. Put in some effort to learn about common interests of the type of people you want to do business with.
- We are in the middle of a generational shift: 33% of millennials got married or entered a long-term partnership in the past five years. This is the first generation where dual-income families are normal.
- Financial products for couples need an update: Many financial products used today were built for single-income households and aren’t adapted for dual-income families.
Tell me about your journey, how did you end up in the Bay Area/tech?
It goes pretty far back. My grandfather started two companies. One he ran for 20 years, and the other for 25 years. Then my parents emigrated to Canada, started this company, and ran it for 18 years. Growing up, I thought most people started companies. It wasn’t until my grade seven careers class, where they walked you through all the different careers and had a chart about the percentage of people in each career, that I realized entrepreneurs are less than 10% of the population. I thought it was a much higher percentage because everyone around my parents was an entrepreneur. I have always been interested in starting businesses. I was that stereotypical kid who kept running side hustles.
I read that your first entrepreneurial endeavor was a fundraiser for UNICEF.
Yeah, it was grade one, and the teacher decided to have a competition to raise money for UNICEF. The idea was to go trick-or-treating using those orange UNICEF boxes to collect donations. I lived in Edmonton at the time, which is the most populated city that far north, so winter was basically already here by Halloween. We had this competition in class to see how much money people could raise, but my parents were really worried my brother and I would get sick if we went trick-or-treating outside when there was already a foot of snow on the ground. I really wanted to make sure I wasn’t going to lose in the UNICEF competition, so instead, I decided to take a bunch of origami, fold it into different shapes like planes and boats, and sell it during recess to the teachers. All the money went to UNICEF. This was my way of being like, “Okay, great, I can do this all the time during recess for a month,” and then raise enough money instead of going trick-or-treating as a workaround for that.
Let’s go back to your story.
I’d already started my own company in high school and had been really involved with startups in university, running a student-run venture fund that organized pitch nights. Because of these experiences, I had the chance to work at the largest VC fund in Canada when I graduated. It was an incredible experience because we got to see a large breadth of startups during that vintage. Some of the companies I personally worked on included Sonder in their pre-seed stage and Hopper in the earlier days. About two years into my time in a venture, my younger brother told me he was thinking of moving to the Bay Area when he graduated from Waterloo. We’re very close, and I wanted to be in the same city as him. Around the same time, I was thinking about applying for jobs. My brother wasn’t going to graduate yet, but I figured I would start looking for a job there. And so I started applying for some jobs and just started talking to more people and getting more involved in the Bay Area.
Right around the same time, Stripe ended up reaching out to me. I had met members of their team, and this was back when the company was like 150 people. The company was much smaller; they had just hired a COO and were just starting to build up their business and growth teams. We chatted about whether I would be interested in joining the stuff they were doing on the growth side. Around the same time, I had gotten connected to Gold House founder Bing Chen. I went to Bing for career advice because I had a couple of other opportunities that were also in the Bay which I was considering. I was 22 years old, trying to figure out what to do with these opportunities in front of me. On top of that, I was potentially moving to another country on the other side of the continent. I don’t even know if Bing will remember this, but it left such a mark on me. He walked me through an exercise he did when he was in university. It was something he found really helpful to understand your own values and what brings you joy.
The exercise he walked me through was to start with an empty piece of paper and write down, in free form, everything that makes you happy. Anything that brings you joy—it can be an item, an exercise, or an activity. I jotted down like 100 different words. Then he said, “Now start to cut it down. Cut it in half. Take the ones that don’t matter. Now you have 50. Now cut it down to 25.” This is when it starts to get really hard. “Now cut it down to 10. Now cut it down to 5.” With the last five words, is there a grounding or a theme that goes through all of it? If those are the things that really bring you joy after you’ve processed this and wondered, that’s probably a very good starting point to think about what you dedicate your time to.
So what were your last five words?
For me, I remember really thinking about how I loved making and empowering. That was one of the words that came out. It was empowering, teaching. I really believed in it. At the time, I had done my CPA and CFA when I was in venture, and I really understood and saw how in the world of finance, things were so opaque. I had also thought a lot about family and friends, and I started thinking about how those words could formulate into almost like my North Star. Big credit to Bing; after I went through that exercise, the answer was very obvious to me. What was so exciting about joining Stripe back in 2015 was that we were really focused on helping SMBs and startups in this opaque world of finance. At the time, payment companies were used to dealing with massive enterprises, so if you were a startup or an SMB, you basically didn’t matter. The products were terrible, it was hard to integrate, and the process of using the product was terrible. For many entrepreneurs, being able to accept money for your product or service is a critical part of running your business. If you don’t have revenue, nothing else works.
For me, it was so obvious that of all the opportunities I had been looking at, Stripe was clearly the best one. Ironically, now in hindsight, I can say this: the other thing that was really crazy was when I decided to join Stripe, I didn’t know my title. I actually forgot to ask what my title was until I received the offer letter. I didn’t even bother asking. I knew what I was going to work on, and I knew who I was going to work with. It was also by far the lowest salary package compared to all the other companies. Given how much Stripe has grown, it’s definitely turned into the best decision. At the time when I joined, it was so clear that it aligned with the things I cared about most. The other things like compensation or title just didn’t matter as much.
You took a sabbatical from work before starting Plenty in 2022. What inspired the sabbatical?
When my parents started their business, they ran it for 18 years. My grandparents ran their businesses for almost 20-25 years. So, I never thought of starting a company as a quick two to three-year journey. I thought it would be a very long journey, and I wanted to feel like I was ready to commit that kind of time and have that kind of endurance. That was one part that was really important. Travel is very important to me–being able to see the world. I knew that if I didn’t have this period of travel, I would always wonder if I missed out.
Part of how I thought about the mental preparation to become a founder is being able to think about how it might feel. One of the parts that helps with the mental endurance of it is being able to realize what might make it harder and, if possible, try to solve some of that earlier. The sabbatical year was basically that. If I didn’t have it, I would look back at the very hard moments when you need to keep going when you’re starting a company and think, “Oh man, maybe I should just stop. Maybe now I can have my travel year because I never had it. Was it worth the sacrifice?” I think it just makes it so much harder instead of getting ahead of it.
What made you feel that it was the right time to start your founder journey?
I think of myself as a lifelong learner. When I experience anything in life, I immediately start to think about what I can learn, what I can do differently, what I would do in the future, and what might have changed the outcome. That is deeply ingrained in who I am. I realized I would probably always feel like there was more to learn and never feel ready.
My mother had a philosophy when she was running her company: you don’t need to do everything personally yourself, but you need to know what great looks like. You need to have enough exposure to know what great products, sales, and marketing look like and have that intuition. You don’t have to do every single thing personally, and frankly, you can’t. There was a point at which I realized I had been exposed to enough people who did their jobs great and did really great work. That shift in mindset was really valuable. I thought, “I might not ever feel ready, and that’s okay, but I’ve also had some experience, so maybe it is time to take a bet on myself.”
For young people who aspire to start their own business in the future, would you say that the function of what they are doing is secondary to who they are around?
Here’s how I approached it when I was at Stripe. I was really lucky because Stripe had an incredibly high talent bar. I was surrounded by so many people. I was also the youngest person on the business team, so I was surrounded by all these people who were 5, 10, 15 years ahead of me career-wise. They were at the top of their game at what they did, and I just tried to be as much of a sponge as possible. I also moved teams a couple of times, which helped with getting exposure to a lot of parts of the organization.
One of the things I’m most grateful for is that Stripe used to have this policy where every email that is sent across teams or externally, is copied to an email list so anyone in the company can read it. It’s complete email transparency. They don’t do this anymore, but for the entirety of the time that I was there, that’s what they did. Also, every single team had to send meeting notes at the end of every meeting to these email lists, and anyone in the company could read the meeting notes. Every one or two months, I would really focus on understanding what another team did. For example, when I was on the sales team, I’d really focus on what the partnership team did and read every single one of their meeting notes for two months. Then I would rotate to another team. I spent a month thinking about risk and compliance, a month reading everything in the world related to the legal side of things, and then I would rotate to what product is doing, what engineering is doing, and how infrastructure works.
It felt like I created my own mini-MBA because I got to see not just the theory but how all functions actually work in a company. I took being a sponge really seriously. It was honestly so fun for me. I know it was rare to have access to all of this knowledge, to have that quality of thought and quality of people around me that I could easily learn from.
Could that be replicated at larger companies?
It’s really only startups where you can get that level of access. Another thing that benefited my learning was that Stripe was growing rapidly while I was there. It grew from a couple hundred to a couple thousand people during my time there. Because it was growing so quickly, I saw many chapters of a startup during that time. There was such an emphasis on communication. Because the company was growing so quickly, documentation was especially critical so that work was not duplicated. That, I think, is one of the unique growth opportunities of being in a startup that is harder to get access to when you’re at a big company.
Given that you come from a family of entrepreneurs, do you find yourself asking your parents and grandparents for business advice?
I definitely talk to them about work a lot more after starting my company. Before I started Plenty, when I talked to them about work, it was sometimes a little frustrating because they’d say, “Why don’t you just ask for the promotion?” I’d be like, “Mom, it doesn’t work like that. You have to earn it and wait your time.” My mom, being an ultra-entrepreneur, thinks it’s exclusively merit-based. In reality, in a big organization, there are performance cycles, and you have to wait six months. You can’t just suddenly say, “I want to be promoted today,” and have a multi-hundred or multi-thousand-person organization just say yes. It doesn’t work like that.
At that time, it was much harder to ask for career advice. But now, it’s really helpful because my parents deeply understand. It’s not even the practical business advice, frankly; it’s the emotional journey. It’s so hard to hire, support someone to perform, deal with a supplier not living up to expectations, or have a backup plan in case things don’t work out. These are all fairly generalizable pieces of advice that have been incredibly helpful. More than anything, starting a company is an extremely lonely experience. It’s been incredible to talk to my parents, not about the specifics like our cost per click, but about the emotional aspects. It’s hard to feel the pressure of needing to have all the answers and supporting your team’s families. They instinctively understand it on an emotional level, which doesn’t need to be explained.
What is the core problem that inspired you to start Plenty?
If you look at the two generations that are going to undergo the largest amounts of change in the next decade, it’s the baby boomers (who we are not optimistic about being able to sell software to), and then the millennial generation. The reality is that millennials are now turning 30, and this chapter from 30 to 40 years old is generally when you find a partner, buy a house, have kids, and get promoted. There’s so much change that happens. If you navigate your finances well during this chapter, you can set yourself up for the rest of your life.
We saw that it’s also the chapter where people want to take their finances more seriously. They’re actively looking for things to do, but if you’re building up to your first million dollars, there aren’t great products or services meant for that. Once you get over a million dollars, there are lots of financial advisors who are really good and can help you, but why would the best financial advisors want to work with clients with less capital? What we saw was that this industry doesn’t have the best people working with the people who arguably need the most help.
The other aspect of Plenty came from personal experience. When Channing and I got engaged, we couldn’t find any products that made it easy for us to manage our money together. We believe very deeply that the best decisions we make as a partnership are the ones we make together, and that financial decisions are very important in unlocking optionality down the road. If there aren’t great products that make it easy for you to work together, then you’re probably going to have a much harder time trying to figure out things in the future too, right? Those two things were the core motivations for starting Plenty.
Why do you think there is a gap in products to help couples manage their finances in tandem?
Nowadays, it’s normal to be dual-income because both people are educated and everything costs more. It’s more fulfilling to feel like you both have careers and jobs, and it might be necessary in order to support a family. At this point, about 80% of this generation are dual-income families and couples.
This used to not be the case. In the two generations before us, the majority of people were single-income families. A lot of the financial products we use today were designed by people who were single-income household members of other single-income households. So it completely makes sense why they designed a lot of joint products the way they did because it used to make sense, but it doesn’t make sense anymore.
One example of this is if you look at American Express or Chase, there is no concept of a joint credit card. You are both legally on the hook for paying the bill, but both of you don’t get to see what you’ve spent. That doesn’t make sense. So if you get a credit card with Chase and add your partner to it, your partner doesn’t even get a login. They can’t see anything, even though they have a credit card with their name on it. American Express is quirky in a different way. We have both of these cards and from personal experience, when you add your partner to an American Express card, they can only see what they spent on their card. They cannot see what you’ve spent on the main card, even though you both share the card.
There are all these little bumps related to access or permission, but it dates back to a time when it was very normal for one person to earn an income, but it’s not very normal anymore. People and couples nowadays expect to have fairly equal access to understanding their money together. It’s not the same as, “Oh, if they know everything, that’s fine. I don’t need to know anything.” That’s just not nearly as common anymore. Nowadays, conversations around family finances are happening with both people being more equal than ever before.
What we also noticed is that because people are getting married later than ever, they are already used to having their own financial accounts. Even after getting married, maybe they open up some things that they share. But it’s a journey towards sharing more of their finances. They still have things under each of our names. A lot of the financial system was built around the reality of the single-income family that had everything fully joined. But that’s just not the case anymore. That has changed especially quickly in the last five years. Five years ago 33% of this generation was married, and now almost 60-70% of this generation is married or in a long-term partnership.
How do you think being Asian has impacted your founder’s journey?
For better or worse, I have been on the other end of bias, but not because I’m Asian. At least, I think not because I’m Asian. But for other reasons, like being part of a husband and wife team. I’ve even had a VC comment about how he would never report to his wife. I don’t think anyone has ever explicitly called out the fact that I was Asian, but it is something that I am aware of. And here’s the reason why. I feel like I have to work extra hard to be relatable, and frankly, there are assumptions that people have.
My husband is from Virginia and his family’s been in the US for a while. Lots of people are surprised when I mention that I’m the sports person in the relationship. I watch basketball, I watch football, I know the players, and he doesn’t watch any of it. Even when we’re in conversations with potential investors, they’re surprised by that. I don’t know why that might be the case, but I joke about it. I say, you probably wouldn’t have expected a short little Canadian Asian female to know this much about football, right?
I do think what you like to talk about is important. When it comes to attracting business partners, of course, the way you think about business and strategy makes people want to work with you. But there’s another aspect to it. If someone feels like you have something in common with them, they think that you can be a friend. Whether or not they want to spend more time with you is actually really impactful for whether or not they want to back you.
I think I’ve always been aware that I have to work extra hard to be relatable, but I don’t try to spend too much time thinking about it beyond thinking of ways that I can support other Asian founders, because it’s not something I can change. Frankly, I just focus on what needs to be done. I’ve always enjoyed football, but I’ve definitely put in the effort to stay aware of what’s going on because I know it is something that is unexpected when I talk about it.
I’ve talked to a few female CEOs whose husbands are also part of the company. Can you comment on what that’s like?
I think it might be happening more frequently as we go along. I mean, it makes a lot of sense, right? There is no one else in your life that you respect, admire, and trust to that degree. Building a startup is not an easy or linear path. In those moments where you’re like, “Oh gosh, what should we do?” not needing to doubt if you’re building with the right person or if you can trust that person is actually so important. It helps stabilize you through the hard moments because you know they’re in it with you, you can trust them completely, and they care about you. That psychological trust is crucial.
–
Plenty is hiring! If you are interested in working with Emily to build financial tools for the modern couple, check out the available job listings here!
Emily has also graciously offered a 3-month free promo code for our readers. If you are interested in trying out Plenty, use code AHNCommunity to get 3 months free. Thank you Emily for joining us!