Awaken* newsletter

September 12, 2024

SHARE:

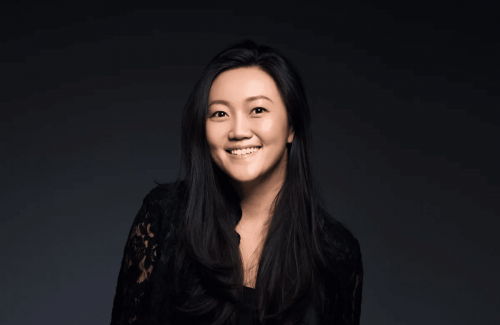
In the half-year I’ve been writing this newsletter I have only interviewed established founders. This article is my first deviation from the pattern and I couldn’t have asked for a better guest. Emily Luk–though a first-time founder–is not new to startups, having joined Stripe as a founding member of their growth team back when the company was around ~150 employees.

Now, she is building Plenty, an investment platform for modern couples. Talking to Emily has convinced me of two things, first–that this is a very large and important problem, second–that Emily is probably the right person to build it. I’m excited to share my conversation with her.

TLDR; Key Takeaways

If you only have a few moments, here are a few golden nuggets from my conversation with Emily:

  • An exercise to find your calling: Write down everything that makes you happy, ~100 words. Keep cutting the list in half until you have five words. What’s the grounding/theme that goes through all five? That’s a good starting point to find your calling.
  • Address opportunity costs before starting a company: Running a successful startup is a long journey, the average time to IPO is 7-10 years. If possible, do the things you’d regret missing out on before embarking on your journey.
  • Aspiring founders should focus on developing taste: As a founder, you don’t need to do everything personally yourself, but you need to know what great looks like. Working alongside great talent can help you develop this intuition.
  • Being relatable is a core part of business: People are much more likely to do business with you if they can relate to you. Put in some effort to learn about common interests of the type of people you want to do business with.
  • We are in the middle of a generational shift: 33% of millennials got married or entered a long-term partnership in the past five years. This is the first generation where dual-income families are normal.
  • Financial products for couples need an update: Many financial products used today were built for single-income households and aren’t adapted for dual-income families.

Tell me about your journey, how did you end up in the Bay Area/tech?

It goes pretty far back. My grandfather started two companies. One he ran for 20 years, and the other for 25 years. Then my parents emigrated to Canada, started this company, and ran it for 18 years. Growing up, I thought most people started companies. It wasn’t until my grade seven careers class, where they walked you through all the different careers and had a chart about the percentage of people in each career, that I realized entrepreneurs are less than 10% of the population. I thought it was a much higher percentage because everyone around my parents was an entrepreneur. I have always been interested in starting businesses. I was that stereotypical kid who kept running side hustles.

I read that your first entrepreneurial endeavor was a fundraiser for UNICEF.

Yeah, it was grade one, and the teacher decided to have a competition to raise money for UNICEF. The idea was to go trick-or-treating using those orange UNICEF boxes to collect donations. I lived in Edmonton at the time, which is the most populated city that far north, so winter was basically already here by Halloween. We had this competition in class to see how much money people could raise, but my parents were really worried my brother and I would get sick if we went trick-or-treating outside when there was already a foot of snow on the ground. I really wanted to make sure I wasn’t going to lose in the UNICEF competition, so instead, I decided to take a bunch of origami, fold it into different shapes like planes and boats, and sell it during recess to the teachers. All the money went to UNICEF. This was my way of being like, “Okay, great, I can do this all the time during recess for a month,” and then raise enough money instead of going trick-or-treating as a workaround for that.

Let’s go back to your story.

I’d already started my own company in high school and had been really involved with startups in university, running a student-run venture fund that organized pitch nights. Because of these experiences, I had the chance to work at the largest VC fund in Canada when I graduated.  It was an incredible experience because we got to see a large breadth of startups during that vintage. Some of the companies I personally worked on included Sonder in their pre-seed stage and Hopper in the earlier days. About two years into my time in a venture, my younger brother told me he was thinking of moving to the Bay Area when he graduated from Waterloo. We’re very close, and I wanted to be in the same city as him. Around the same time, I was thinking about applying for jobs. My brother wasn’t going to graduate yet, but I figured I would start looking for a job there. And so I started applying for some jobs and just started talking to more people and getting more involved in the Bay Area. 

Right around the same time, Stripe ended up reaching out to me. I had met members of their team, and this was back when the company was like 150 people. The company was much smaller; they had just hired a COO and were just starting to build up their business and growth teams. We chatted about whether I would be interested in joining the stuff they were doing on the growth side. Around the same time, I had gotten connected to Gold House founder Bing Chen. I went to Bing for career advice because I had a couple of other opportunities that were also in the Bay which I was considering. I was 22 years old, trying to figure out what to do with these opportunities in front of me. On top of that, I was potentially moving to another country on the other side of the continent. I don’t even know if Bing will remember this, but it left such a mark on me. He walked me through an exercise he did when he was in university. It was something he found really helpful to understand your own values and what brings you joy. 

The exercise he walked me through was to start with an empty piece of paper and write down, in free form, everything that makes you happy. Anything that brings you joy—it can be an item, an exercise, or an activity. I jotted down like 100 different words. Then he said, “Now start to cut it down. Cut it in half. Take the ones that don’t matter. Now you have 50. Now cut it down to 25.” This is when it starts to get really hard. “Now cut it down to 10. Now cut it down to 5.” With the last five words, is there a grounding or a theme that goes through all of it? If those are the things that really bring you joy after you’ve processed this and wondered, that’s probably a very good starting point to think about what you dedicate your time to.

So what were your last five words?

For me, I remember really thinking about how I loved making and empowering. That was one of the words that came out. It was empowering, teaching. I really believed in it. At the time, I had done my CPA and CFA when I was in venture, and I really understood and saw how in the world of finance, things were so opaque. I had also thought a lot about family and friends, and I started thinking about how those words could formulate into almost like my North Star. Big credit to Bing; after I went through that exercise, the answer was very obvious to me. What was so exciting about joining Stripe back in 2015 was that we were really focused on helping SMBs and startups in this opaque world of finance. At the time, payment companies were used to dealing with massive enterprises, so if you were a startup or an SMB, you basically didn’t matter. The products were terrible, it was hard to integrate, and the process of using the product was terrible. For many entrepreneurs, being able to accept money for your product or service is a critical part of running your business. If you don’t have revenue, nothing else works.

For me, it was so obvious that of all the opportunities I had been looking at, Stripe was clearly the best one. Ironically, now in hindsight, I can say this: the other thing that was really crazy was when I decided to join Stripe, I didn’t know my title. I actually forgot to ask what my title was until I received the offer letter. I didn’t even bother asking. I knew what I was going to work on, and I knew who I was going to work with. It was also by far the lowest salary package compared to all the other companies. Given how much Stripe has grown, it’s definitely turned into the best decision. At the time when I joined, it was so clear that it aligned with the things I cared about most. The other things like compensation or title just didn’t matter as much.

You took a sabbatical from work before starting Plenty in 2022. What inspired the sabbatical?

When my parents started their business, they ran it for 18 years. My grandparents ran their businesses for almost 20-25 years. So, I never thought of starting a company as a quick two to three-year journey. I thought it would be a very long journey, and I wanted to feel like I was ready to commit that kind of time and have that kind of endurance. That was one part that was really important. Travel is very important to me–being able to see the world. I knew that if I didn’t have this period of travel, I would always wonder if I missed out.

Part of how I thought about the mental preparation to become a founder is being able to think about how it might feel. One of the parts that helps with the mental endurance of it is being able to realize what might make it harder and, if possible, try to solve some of that earlier. The sabbatical year was basically that. If I didn’t have it, I would look back at the very hard moments when you need to keep going when you’re starting a company and think, “Oh man, maybe I should just stop. Maybe now I can have my travel year because I never had it. Was it worth the sacrifice?” I think it just makes it so much harder instead of getting ahead of it.

What made you feel that it was the right time to start your founder journey? 

I think of myself as a lifelong learner. When I experience anything in life, I immediately start to think about what I can learn, what I can do differently, what I would do in the future, and what might have changed the outcome. That is deeply ingrained in who I am. I realized I would probably always feel like there was more to learn and never feel ready.

My mother had a philosophy when she was running her company: you don’t need to do everything personally yourself, but you need to know what great looks like. You need to have enough exposure to know what great products, sales, and marketing look like and have that intuition. You don’t have to do every single thing personally, and frankly, you can’t. There was a point at which I realized I had been exposed to enough people who did their jobs great and did really great work. That shift in mindset was really valuable. I thought, “I might not ever feel ready, and that’s okay, but I’ve also had some experience, so maybe it is time to take a bet on myself.”

For young people who aspire to start their own business in the future, would you say that the function of what they are doing is secondary to who they are around?

Here’s how I approached it when I was at Stripe. I was really lucky because Stripe had an incredibly high talent bar. I was surrounded by so many people. I was also the youngest person on the business team, so I was surrounded by all these people who were 5, 10, 15 years ahead of me career-wise. They were at the top of their game at what they did, and I just tried to be as much of a sponge as possible. I also moved teams a couple of times, which helped with getting exposure to a lot of parts of the organization.

One of the things I’m most grateful for is that Stripe used to have this policy where every email that is sent across teams or externally, is copied to an email list so anyone in the company can read it. It’s complete email transparency. They don’t do this anymore, but for the entirety of the time that I was there, that’s what they did. Also, every single team had to send meeting notes at the end of every meeting to these email lists, and anyone in the company could read the meeting notes. Every one or two months, I would really focus on understanding what another team did. For example, when I was on the sales team, I’d really focus on what the partnership team did and read every single one of their meeting notes for two months. Then I would rotate to another team. I spent a month thinking about risk and compliance, a month reading everything in the world related to the legal side of things, and then I would rotate to what product is doing, what engineering is doing, and how infrastructure works.

It felt like I created my own mini-MBA because I got to see not just the theory but how all functions actually work in a company. I took being a sponge really seriously. It was honestly so fun for me. I know it was rare to have access to all of this knowledge, to have that quality of thought and quality of people around me that I could easily learn from.

Could that be replicated at larger companies?

It’s really only startups where you can get that level of access. Another thing that benefited my learning was that Stripe was growing rapidly while I was there. It grew from a couple hundred to a couple thousand people during my time there. Because it was growing so quickly, I saw many chapters of a startup during that time. There was such an emphasis on communication. Because the company was growing so quickly, documentation was especially critical so that work was not duplicated. That, I think, is one of the unique growth opportunities of being in a startup that is harder to get access to when you’re at a big company.

Given that you come from a family of entrepreneurs, do you find yourself asking your parents and grandparents for business advice?

I definitely talk to them about work a lot more after starting my company. Before I started Plenty, when I talked to them about work, it was sometimes a little frustrating because they’d say, “Why don’t you just ask for the promotion?” I’d be like, “Mom, it doesn’t work like that. You have to earn it and wait your time.” My mom, being an ultra-entrepreneur, thinks it’s exclusively merit-based. In reality, in a big organization, there are performance cycles, and you have to wait six months. You can’t just suddenly say, “I want to be promoted today,” and have a multi-hundred or multi-thousand-person organization just say yes. It doesn’t work like that. 

At that time, it was much harder to ask for career advice. But now, it’s really helpful because my parents deeply understand. It’s not even the practical business advice, frankly; it’s the emotional journey. It’s so hard to hire, support someone to perform, deal with a supplier not living up to expectations, or have a backup plan in case things don’t work out. These are all fairly generalizable pieces of advice that have been incredibly helpful. More than anything, starting a company is an extremely lonely experience. It’s been incredible to talk to my parents, not about the specifics like our cost per click, but about the emotional aspects. It’s hard to feel the pressure of needing to have all the answers and supporting your team’s families. They instinctively understand it on an emotional level, which doesn’t need to be explained.

What is the core problem that inspired you to start Plenty?

If you look at the two generations that are going to undergo the largest amounts of change in the next decade, it’s the baby boomers (who we are not optimistic about being able to sell software to), and then the millennial generation. The reality is that millennials are now turning 30, and this chapter from 30 to 40 years old is generally when you find a partner, buy a house, have kids, and get promoted. There’s so much change that happens. If you navigate your finances well during this chapter, you can set yourself up for the rest of your life.

We saw that it’s also the chapter where people want to take their finances more seriously. They’re actively looking for things to do, but if you’re building up to your first million dollars, there aren’t great products or services meant for that. Once you get over a million dollars, there are lots of financial advisors who are really good and can help you, but why would the best financial advisors want to work with clients with less capital? What we saw was that this industry doesn’t have the best people working with the people who arguably need the most help.

The other aspect of Plenty came from personal experience. When Channing and I got engaged, we couldn’t find any products that made it easy for us to manage our money together. We believe very deeply that the best decisions we make as a partnership are the ones we make together, and that financial decisions are very important in unlocking optionality down the road. If there aren’t great products that make it easy for you to work together, then you’re probably going to have a much harder time trying to figure out things in the future too, right? Those two things were the core motivations for starting Plenty.

Why do you think there is a gap in products to help couples manage their finances in tandem?

Nowadays, it’s normal to be dual-income because both people are educated and everything costs more. It’s more fulfilling to feel like you both have careers and jobs, and it might be necessary in order to support a family. At this point, about 80% of this generation are dual-income families and couples. 

This used to not be the case. In the two generations before us, the majority of people were single-income families. A lot of the financial products we use today were designed by people who were single-income household members of other single-income households. So it completely makes sense why they designed a lot of joint products the way they did because it used to make sense, but it doesn’t make sense anymore. 

One example of this is if you look at American Express or Chase, there is no concept of a joint credit card. You are both legally on the hook for paying the bill, but both of you don’t get to see what you’ve spent. That doesn’t make sense. So if you get a credit card with Chase and add your partner to it, your partner doesn’t even get a login. They can’t see anything, even though they have a credit card with their name on it. American Express is quirky in a different way. We have both of these cards and from personal experience, when you add your partner to an American Express card, they can only see what they spent on their card. They cannot see what you’ve spent on the main card, even though you both share the card. 

There are all these little bumps related to access or permission, but it dates back to a time when it was very normal for one person to earn an income, but it’s not very normal anymore. People and couples nowadays expect to have fairly equal access to understanding their money together. It’s not the same as, “Oh, if they know everything, that’s fine. I don’t need to know anything.” That’s just not nearly as common anymore. Nowadays, conversations around family finances are happening with both people being more equal than ever before. 

What we also noticed is that because people are getting married later than ever, they are already used to having their own financial accounts. Even after getting married, maybe they open up some things that they share. But it’s a journey towards sharing more of their finances. They still have things under each of our names. A lot of the financial system was built around the reality of the single-income family that had everything fully joined. But that’s just not the case anymore. That has changed especially quickly in the last five years. Five years ago 33% of this generation was married, and now almost 60-70% of this generation is married or in a long-term partnership.

How do you think being Asian has impacted your founder’s journey? 

For better or worse, I have been on the other end of bias, but not because I’m Asian. At least, I think not because I’m Asian. But for other reasons, like being part of a husband and wife team. I’ve even had a VC comment about how he would never report to his wife. I don’t think anyone has ever explicitly called out the fact that I was Asian, but it is something that I am aware of. And here’s the reason why. I feel like I have to work extra hard to be relatable, and frankly, there are assumptions that people have.

My husband is from Virginia and his family’s been in the US for a while. Lots of people are surprised when I mention that I’m the sports person in the relationship. I watch basketball, I watch football, I know the players, and he doesn’t watch any of it. Even when we’re in conversations with potential investors, they’re surprised by that. I don’t know why that might be the case, but I joke about it. I say, you probably wouldn’t have expected a short little Canadian Asian female to know this much about football, right? 

I do think what you like to talk about is important. When it comes to attracting business partners, of course, the way you think about business and strategy makes people want to work with you. But there’s another aspect to it. If someone feels like you have something in common with them, they think that you can be a friend. Whether or not they want to spend more time with you is actually really impactful for whether or not they want to back you.

I think I’ve always been aware that I have to work extra hard to be relatable, but I don’t try to spend too much time thinking about it beyond thinking of ways that I can support other Asian founders, because it’s not something I can change. Frankly, I just focus on what needs to be done. I’ve always enjoyed football, but I’ve definitely put in the effort to stay aware of what’s going on because I know it is something that is unexpected when I talk about it.

I’ve talked to a few female CEOs whose husbands are also part of the company. Can you comment on what that’s like?

I think it might be happening more frequently as we go along. I mean, it makes a lot of sense, right? There is no one else in your life that you respect, admire, and trust to that degree. Building a startup is not an easy or linear path. In those moments where you’re like, “Oh gosh, what should we do?” not needing to doubt if you’re building with the right person or if you can trust that person is actually so important. It helps stabilize you through the hard moments because you know they’re in it with you, you can trust them completely, and they care about you. That psychological trust is crucial.

–

Plenty is hiring! If you are interested in working with Emily to build financial tools for the modern couple, check out the available job listings here!

Emily has also graciously offered a 3-month free promo code for our readers. If you are interested in trying out Plenty, use code AHNCommunity to get 3 months free. Thank you Emily for joining us!
Related Articles

Stories

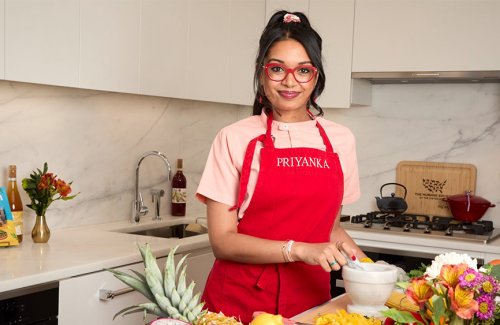
Creators Podcast: Chef Priyanka Naik Makes Waves in Vegan Cooking

AHN and Meta Prosper have partnered on a new podcast series highlighting API creators. Meta Prosper is dedicated to amplifying and supporting the API community and driving economic growth and equitable representation. The Creators Podcast series delivers stories on how creators achieved success and created impact through their platforms, serving as an inspiration for the community.

In the first installment of the Creators Podcast series, we shine a spotlight on Priyanka Naik, a first-generation Indian-American whose path took her from pre-med and economics to a career in media and tech, before going full-time into the culinary world.

Priyanka Naik is a self-taught award-winning vegan chef who grew up in New York, incorporating her family heritage into her plant-based cooking. But she didn’t stop there.


Drawing inspiration from her travels to over forty countries, Priyanka infuses each place she visited into her recipes while focusing on sustainability. She practices no-waste cooking and consciously sources ingredients to minimize her environmental impact, making her a leading advocate for eco-friendly culinary practices. 

Priyanka’s cooking skills have landed her on TV shows like The Today Show and The Kelly Clarkson Show, and have led her to become a Food Network champion, TV host, author of The Modern Tiffin, columnist for Ecokitchen in The Washington Post, pop-up restaurateur, and a TEDx speaker.

Listen to The Creators Podcast featuring Priyanka Naik here.

CONNECT WITH CHEF PRIYANKA NAIK

Instagram: @chefpriyanka

Facebook: Chef Priyanka Naik

Threads: @chefpriyanka

Anna Fang

Awaken* newsletter

Candid Conversations on Venture Capital and Entrepreneurship with Anna Fang

Anna Fang is the CEO of ZhenFund, an early-stage venture fund that has invested in over 600 startup companies, particularly in e-commerce and AI, with successful investments in unicorns like RED (XiaoHongShu), Perfect Diary, and Horizon Robotics. Anna began her career in investment banking at JPMorgan in New York City and later helped expand M&A efforts at GE China before joining ZhenFund in 2011.

In a recent interview with AHN Ventures, Anna shared insights about her venture capital journey, the high standards ZhenFund maintains for selecting founders, and the evolving landscape of early-stage investments. Read through to learn more:

HanYue: What inspired you to start Zhen Fund?

Anna: I began building Zhen Fund in 2011 after a significant tenure at GE. The catalyst was a conversation with a Graduate School of Business friend who was with Sequoia China about initiating a Y Combinator-like model in China. During this period, I met Mr. Xiaoping Xu, whose vision was truly inspiring. Additionally, the vast opportunities in China’s entrepreneurial landscape were too compelling to ignore.

HanYue: You are one of the pioneers in China’s venture capital industry. How has being an investor changed over the years?

Anna: Ten years ago, being a VC wasn’t as glamorous as being a private equity or angel investor. The scene was quieter. Entrepreneurship wasn’t as trendy, so it was easier to find thoughtful, high-caliber founders. Our first fund was $15 million, and we made 16 investments, including Xiao Hong Shu, which topped lifestyle app charts, and Huobi, HTX, which became China’s largest crypto exchange, and Deeplint, which went public. The VC scene entered a hype cycle from 2014 to 2020, with an overwhelming amount of money chasing deals. It felt wasteful to me. Now, with a ‘VC winter,’ I appreciate the slower pace that allows for more selective investments.

HanYue: Can you discuss the high standards Zhen Fund maintains when selecting founders?

Anna: There’s a high bar, especially for AI nowadays. Founders must deeply understand the technology. For example, we invested in Zhilin Yang, a renowned and famous PhD.  Zhilin Yang is the founder of Moonshot AI, with a ChatGPT-like product Kimmy Chat.When I was looking for interns, there are kids these days who would say ‘whoa, you invested in Dr. Yang? That’s so cool. I want to work for you.’ Interns want to work for us because we invested in Yang, that was really something special.

HanYue: Yodu achieved many significant successes with your first fund. What excites you currently?

Anna: Lately, I’m fascinated by AGI and the global integration of foundational models into robotics. There’s also a burgeoning interest in applications built on these models, alongside video and productivity apps like monaco.im and max.me. Observing how human and AI co-pilots can coexist and interact is particularly intriguing.

HanYue: You’ve invested in many successful founders. What traits do they share?

Anna: It all boils down to hustle – your organization’s name Asian Hustle Network really speaks volume by the way. Successful founders are not afraid to get out there and continue to network. They have an infectious enthusiasm. Even I had to do it once. When I was just getting started, I would put ‘send me deals’ directly in my email signature.

HanYue: What challenges do early-stage startups typically face, and what advice do you have for navigating these challenges?

Anna: All successful companies have experienced moments where they almost didn’t survive, be it due to regulatory issues, cash flow problems, or founder conflicts. My advice is not to be phased by difficulties. Believe that you will pull through. Having mentorship is also crucial as it provides support and helps solve problems together.

One thing I really love about angel investing is the thrill of being the first to adopt new and innovative ideas, always staying alert and aware of emerging trends. Emma and I often joke about not being the top students at Stanford, always admiring how incredibly smart our classmates are. 

Bob taught me the essentials: reviewing the team page – I often feel like an admissions officer searching for predictors of future success. It’s like trying to find Yao Ming among a crowd of tall people—a search for standout talent in a field of strong contenders. 

With everything changing so fast, I am more excited about looking for really thoughtful founders. For example, I am really excited about this one young man, who used to my intern, he could just sit there and talk about the macroeconomy trends forever. And the way he thinks about what might become popular among young people continues to impress me. For example: The younger generation embraces ‘YOLO’—living in the present. And as a founder, you will need to think about new hobbies and cultural shifts that might emerge, and find ways to take advantage of that. 

HanYue: As a lecturer at GSB and a seasoned investor, how do you differentiate in a crowded VC landscape?

Anna: Our differentiation lies in our founder-first approach and our simplified, transparent investment process. Even when we pass on an investment, we provide thoughtful feedback. Zhen Fund is not just about funding; it’s about fostering a community and offering programs like the EIR and Ostrich Club that systematically identify and support potential top founders. We want to build a supportive community. 

Edwin: What trends from China do you see influencing the US, and vice versa?

Anna: E-commerce platforms like Shein and Temu are leading trends, with TikTok’s integration of e-commerce being particularly noteworthy. We’re also seeing interest in replicating China’s online education model and infrastructure globally. Additionally, attempts to mimic the success of businesses like Luckin Coffee in various international markets highlight the growing influence of Chinese business models abroad.

Eric Wei and Will Kim

Awaken* newsletter

A Candid Conversation with Karat’s Co-Founders on Entrepreneurship and Authenticity

Karat Financial is a startup that provides banking services to content creators. At first glance, you may think this is a non-issue, but consider that popular chess streamer Alexandra Botez was rejected twice when applying for a business credit card, despite bringing in over $100,000 a year through her content. Clearly, investors also agree that this is an issue. Karat has raised over $100 million from top-tier investors such as SignalFire, USV, and GGV.

I had the honor to chat with Eric Wei and Will Kim, the co-founders of Karat. Eric and Will exemplify an ideal co-founder relationship, and I found them to be extremely thoughtful and insightful. Let’s get into it:

ENTREPRENEURIAL BEGINNINGS

Both Eric and Will have been entrepreneurs long before they had even thought up the idea for Karat. I asked them to talk about what their first entrepreneurial endeavors were:

Eric: I was going to say, Will was actually recognized in high school by President Obama for one of his early entrepreneurial efforts. Will, why not share?

Will: Sure. That was in high school. President Obama found out about this micro-lending organization I made, where I was lending money to high school students and underserved areas within the Bay, Oakland, Emeryville in particular, to high school entrepreneurs. I would say, “If I give you 500 bucks to start this business model that you have in mind, you’re going to pay me back after you make the money and we’re all going to be happy.” The lead up into that was just hearing about Kiva in an SAT prep book and thinking, “This is such a cool idea.” Kiva is a micro-lending platform that was taking off back in the early 2010s. I thought, “This is a cool idea. I’m going to intern for them.” I realized pretty quickly that interning for them is not as fun as just doing it myself. So I started my own micro-lending organization within the Bay. I saw the same wealth and equity problems that micro-lending is supposed to solve exist in the Bay, just as in these third-world countries. And I ran with it. What I quickly learned is that it’s actually very hard to execute well on what seems like a great idea. I found out the hard way. It’s easy to give money. It is a lot harder to get the money back. That was a kind of helpful testing ground for me. Eric, we’ve experimented with a number of ideas right before, haven’t we?

Eric: Yes, we have. I can share some quick context, too, from my side. One, just want to say, it’s pretty incredible that Will built a functioning company just as a high school student that continues to operate today. Even some of my Harvard classmates, actually, I remember there’s a guy I knew from Harvard. He graduated and he ended up working there. I was like, “Wow, this guy who was just a high school student built an institution that continues to perform and recruit quality people.” I’m not surprised Obama recognized him. It’s cool to build something that lasts and sustains, that’s trying to improve the financial system, but also something that’s just straight up helping people. I think that’s just really, really cool. I was reading about microfinance models like the Grameen Bank and such, and here Will was actually doing it. So I really, really just love how he did that. It’s one of the things I appreciated about him very early. On my side, similarly to Will, my early entrepreneurial efforts were also aimed at how we improve the financial system as it is. One of the very first things I worked with when I was at Harvard was on income share agreements. Now, they’ve become much more popular in the past, say, five, ten years. The concept is that you can fund your education or whatever vocational training you’d like, not just by taking out loans, but by promising to share a portion of your future income and revenue. And the whole thing is, in many cases, it’s going to be a more favorable repayment structure because, say, for whatever reason, you go through this training, this education, and you don’t end up getting a well-paying job afterwards. Well, it’s not really fair to put this burden, this onerous loan on you that you have to pay back. It might be easier if it’s just a percentage of whatever you did make. And my sophomore, and junior years at Harvard, I put together a team with JP Morgan bankers, and McKinsey consultants to go and pioneer this concept. We even pitched the president of Harvard, Drew Gilpin Faust, at the time. It didn’t work, mainly because it was extremely complicated from a regulatory point of view. Many of the companies also exploring educational ISAs at the time actually ended up pivoting. A great example is this company called Upstart which initially was also focused on this, and has since pivoted back to more traditional lending and just saying, hey, we have a better underwriting model, so we can give you better rates, but still loans rather than ISAs. That’s why, to my earlier point, similarly to Will, it gave me a glimpse into a lot of how this world works. It’s people deciding to give money to each other, where the rich have the most capital and they’re trying to get it to the people that ultimately need it the most. But for the people who need it the most, because they’ve gotten that money through so many layers, it’s so expensive for them. So you can try to improve that by building better underwriting mechanisms or by trying to go more directly from the people with money to those who don’t have it. 

Looking back, I think Will and I both had versions of that as some of our earliest entrepreneurial efforts, which I just think is really cool. And then to Will’s previous point, we worked together on a lot of products before Karat as well. I think it was a shared passion in not only wanting to start something of our own but also something along the lines of, hey, in life, there’s much more that matters than just money. When I met Will, he was coming off an internship at Goldman Sachs and was running a venture firm. I was coming from Blackstone and McKinsey and just starting a tech job. Both of us could have chosen to stay in finance and frankly, made much more on a risk-adjusted basis than any other occupation. And both of us saw something and, hey, but there’s some meaning that I can have in helping others. And what does that look like? So we started to work together, went through a lot of different projects, and ultimately decided to focus on working with creators and helping them navigate the financial system.

THE BUSINESS OF KARAT

I asked why Eric and Will decided to focus on creators and how they went about getting their first customers:

Will: In business, the best way to win is to play games that you make up. We’re trying to make up games in areas where they don’t exist because other people don’t know about them–it’s a secret. For us, that secret was that creators are businesses. And that was really, really compelling. It felt like everyone was writing off these creators as businesses back in 2017/2018 when we were first looking at creators; but, these were real businesses. 

Eric: Very early on, the most important thing was to go to where the creators were and just talk to them. So Will and I would go to conferences like VidCon and TwitchCon, and we just cold approached people and just asked them, hey, what are you most focused on these days? What’s the dream? What are the biggest problems that you’re facing? 

I think there’s an easy tendency to think a lot about overall strategy without just literally talking to people, right? No plan survives first contact with the enemy. And what I realized really early on was that creators are trying really, really hard to figure out how to make content, make money, and build a business.

The creator community has many individuals who are operating businesses, but they have no idea how to handle the business’ financial setup. Through these early insights, Will and I prototyped the first thoughts of what Karat could be. When we finally had actual products, we went back to many of the people we met and asked if they would try them. When they had a good experience, they would share it organically via word of mouth. One thing I’m proud about Karat is that we’ve never really done influencer marketing programs. It’s primarily just been organic and referral-focused. Creators especially are more likely to share because it’s what they do on a day-to-day basis.

Will: I remember Eric was wearing his Instagram shirt. He optimized every single element of this to make sure that we could make something out of nothing, which is incredibly difficult. Eric was pulling out all the tricks out of his bag. 

Eric: I used to work at Instagram. If you wear an Instagram shirt, people are more likely to chat with you. There are tons of hacks to this. For example, you go to a conference and a creator is speaking. At the end of that panel, run up and be the very first one to talk with them. Big creators, a lot of times, have fan meeting greets, where you wait in line. We would use that to pitch them. We would be absolutely shameless, asking very business-focused questions. Some people didn’t like the concepts we were going through. But that means you actually have a firm point of view. If you find something that some people don’t like, but some people actually really do, that’s promising. 

Edwin: I resonate with that. For some of the guests that I’ve had on the interview before, that’s what I had to do. Go to those events and say, hey, I sent you an email. You didn’t respond to it. 

Eric: Even if it rubs them the wrong way, in the end, you’re just trying to build something from scratch. It’s better to try than to not try at all. I greatly admire and respect the determination with which you followed up. When I had a free moment, I remembered and emailed back. And then to have you respond back instantly, I was very impressed. That’s a big reason why I was excited to share more for this newsletter and to build a relationship with you personally.

I really appreciate Eric’s endorsement of my tactics. As a side note, I also find it awkward and difficult to do this kind of cold pitching sometimes, it requires being very vulnerable. However, I have two thoughts about this. Firstly, cold outreach is like a muscle you train, the first time you go to the gym is going to be awkward, and the 100th time is second-nature. Secondly, if you really want to reach someone why wouldn’t you try multiple times, why wouldn’t you try every mode of contact you can find (email, phone call, mail)–this seems like table stakes. Though obviously, please stop if they aren’t interested, and don’t harass anyone.

I was also curious how Eric and Will came up with the business model for Karat, as the intersection of creators and fintech hadn’t been explored much before them:

Eric: From a people perspective, we worked with creators like Alexandra Botez, a top chess streamer who graduated from Stanford, started a company, and has over a million followers on Twitch. She was rejected for a business credit card multiple times because they just didn’t understand what she was doing. When you hear a problem like that, you start questioning if the current system is optimal. The answer is no because making a living as a creator is so new, that the existing financial system, which is built on traditional criteria, doesn’t evaluate it properly. From a systems POV, if everyone is thinking about making content going forward, everyone is learning how to be a creator, every business is learning how to use content, and getting to build the financial picks and shovels that facilitate money moving around could be a huge opportunity. We want every dollar in the creator economy to pass through Karat, whether it’s through our payment systems, credit cards, bank accounts, and more.

Will: When we first realized that creators are businesses, that felt like a secret. But the deeper secret that excites us is that we believe in the future, all businesses will have to have some kind of creator angle. This felt like a massive unlock. Procter & Gamble became a generational company because it capitalized on the advent of cable television. Now, creators own the airways and they have the cheapest distribution to their fanbase. They’re going to be able to out-compete Proctor & Gamble and make the new Proctor & Gambles. That’s very exciting. To Eric’s point, if we can sell the picks and shovels there–if we can be the financial rails, that’s going to crush.

Eric: A really good example of that, for instance, is if you’re familiar with Under the Influence and the seltzer brand Nectar. They’re an example of a company that developed a hard seltzer to compete against White Claw. To advertise it, they developed a podcast. The podcast has become so popular that its hosts were actually signed to an agency. Many of the people who watch the podcast think that the seltzer is just the brand sponsoring the podcast. It was actually the other way around. The podcast is the content marketing arm of a consumer packaged goods company because the founders grew up in social media. To Will’s point, the future Proctor & Gambles are going to be people who are building businesses with content built-in natively from day one.

RUNNING A STARTUP

The next question I asked the duo was how they deal with the mental stress of running a startup:

Will: First of all, I haven’t completely figured it out. I just have to deal with it. The quote I live by and come back to a lot is from Eddie Merckx, one of the world’s fastest cyclists ever. Reporters asked him how it felt to be so fast, and he said, “It doesn’t get easier. You just get faster.” That’s it. As we’ve scaled up, we’ve only run into more issues, and more challenges. Eric loves the quote, “The prize for eating humble pie is eating more humble pie.” I believe that’s true. So, it’s about accepting that’s the reality. Personally, I’ve been sticking to routines like simple stuff. Cold showers are nice. Waking up early is nice. Being able to meditate is nice. Reading Marcus Aurelius is nice. That works for me, and I stick to it. It’s pretty straightforward, but it works for me.

Eric: As founders, we obviously have to care a lot about financial runway, because presumably, we’re building something with a shot at being really big. Early on, it’s going to cost money. But what people forget is the emotional runway. Money is useless and pointless if you’re not in a place to be creative, brave, and determined to try and do things with it. In terms of how you maintain that emotional runway, it’s really different for everyone. For me, one of the things that really helps is my relationship with Will. There are many solo founders out there that I respect and think very highly of. I know confidently that I could not have done Karat without Will. We’re not only co-founders but also co-CEOs, which is why you get both of us here today instead of just one of us. We’ve found that if one of us is feeling very down, the other is usually not feeling as down. It’s very rare we both feel down at the same time, which is bad because then everything just kind of falls apart. But I’ve found him to be very helpful, not only from an emotional point of view, balancing when I’m sad and not sure if something’s going to work, but also when I’m really excited to sort of temper it because, at the start of the plan, everything changes so quickly. But also just to know that there’s someone else who cares just as much, if not more, than I do about this. I think that’s a relieving burden on a founder’s shoulders. Of course, it comes with its own consequences. To be clear, I think there’s also more complexities when you have a co-founder and co-CEO. Nothing in life is just a free lunch. Sure, you get to benefit from each other, but it also means you have to figure out what to do when you disagree.

The fact that Eric and Will were co-CEOs kind of blew my mind because I was taught at a young age that one person should be at the helm of the ship, obviously, I had to ask how they decided to be co-CEOs:

Will: It was pretty simple. We both want to build something cool. We both want to build something big. We have different personalities and skill sets, but we’re aligned on the general values. And why wouldn’t you want to have each other as equals? We’re not hierarchical. It’s not like one of us reports to the other, right? So why not just formalize it if it’s something you truly believe in from a title perspective and an equity perspective?

Edwin: That makes sense. I assume that you guys probably have different strengths. So is there some way that you guys divide the work? Or is it on a case-by-case basis?

Will: I think it’s just case-by-case because our strengths, as a founder, the most important thing is that you scale, that we grow with feedback, that we change with the environment. Stasis is death. And so it’s really, really important for us to always be responsive, not only to the business and the market, but to our own interests, desires, and strengths. For me, I really enjoy thinking about how we can build a system that last. The ideal business to me is one which doesn’t need me, one that already has a large market, that has a system in place, and a product that people want, where I am just icing on top rather than a core element. For me that’s really exciting, so that’s where I like to spend my time.

Eric: Will has always been a really good systems thinker. And again, these are generalities, because both of us have taken opposite approaches from what we’re describing to you now. But for me, there’s a certain satisfaction I get just from going and talking with someone and getting a quick sense if something is going to work or not. This speaks to the nature of a startup. You want to make sure that the people you’re building for actually care, and the fastest way of finding out is to literally go and interact with them. Also, for a venture-scale startup, you need to think about how those initial insights can potentially turn into a billion-dollar business. That needs to be something that can scale into a system.

BEING AUTHENTIC

When researching Eric and Will, one thing that stood out to me was how honest they were with their motivations behind building a company. In articles online, they were very transparent that ego and financial upside were partial motivations for building a company. I asked them how they reached this point of authenticity:

Eric: Something I’ve learned is that there’s literally no point doing anything if you can’t just be immediately straightforward and honest about it. Life’s too short to do things that you’re lying to yourself about or to others. If you care about yourself, you’ll be honest to yourself. If you care about others, you’ll be honest to them. It’s the very same reason I started this call up being like, one, I was super excited. Two, I was impressed by your dedication. And three, here’s something I didn’t love, and here’s why. Because if you want to invest in a relationship with each other, you have to be honest from the start. So, let’s extend this to why build a company. Obviously, Will and I would not be doing this if all we were optimizing for was the financial upside. He would have stayed at Goldman Sachs, I would have stayed at Blackstone. So, there’s a huge motivation around building something that’s better, that can help creators. And to your point, that doesn’t mean our other motivations aren’t real as well. Of course, Will and I are excited about the potential monetary upside of building a successful company, the ego that comes from, hey, we’re going to try to do something new and something of our own. Because from my perspective, that’s real. There’s no shame in that. And I’d much rather present myself as the whole set of motivations I am as a human and as a company. In fact, I don’t trust people who aren’t honest about why they do things. Those are the ones that I’m like, hmm, there’s something you’re hiding from me. If you’re hiding this from me, I don’t know if I can trust you.

Will: When Eric and I were getting close, I started realizing that when I’m talking with Eric, I can be pretty open. I remember at one moment, I just thought, “I can trust Eric with everything. This is the one guy that I can start a business with that would actually make sense.” When we started the business together, it became a really pivotal thing for me because Eric was so vulnerable and shared a lot. We had that kind of relationship that was fully open and transparent. I don’t know why you would ever start a business with someone you don’t trust entirely. In fact, I’d say it to people reading this and thinking about who they partner with: if you don’t trust them, don’t do it. I can say that from personal experience. It’s not worth it. 

Edwin: I think that’s really cool how you guys are very open. I think about how trusting and communicative your relationship is. I took a class in my last quarter at Stanford and basically, the whole point of the class is if people see models of really trusting relationships and open relationships, they’re probably more likely to mimic that and act that way. When you act that way, you’re showing other people to do that, and so on. So that’s really cool that you guys do that. I think there’s a benefit to everyone else beyond just you guys when you do that. 

Will: I hope it goes viral. Viral vulnerability would be very nice where we could all actually trust each other and make the world slightly better. It sucks when you have to always put up this defensive shield. I think frankly, before I met Eric, I walked around life with a defensive shield expecting that everyone’s out there to hurt me. Over time, I realized that if I open myself up, I invite far more excitement, joy in my life, and opportunity as well. 

Eric: I’ll add, if everyone seems to be a giant jerk to you, sometimes that can lead you to put your guard up. But in a weird way, that attracts more people who might not be the best to you because you yourself are not sharing. If you go around and you’re open to people, you’re more likely to find other people who are open. If someone’s open and honest, why would they want to interact with someone who’s hiding things? 

I asked Eric and Will how they extend their mindset around authentic relationships to their relationship with their employees:

Will: We are trying to continue to push this idea of appropriate authenticity in the workplace. The challenge that exists is that there is a power dynamic. Eric and I are peers and so we can be fully open, fully honest, fully transparent. With our team, there is an appropriate level of authenticity. Of course, we want to tell everything about the core business, but is it appropriate for me to say I feel really sad and pissed about all this stuff? Probably not. It creates fear because I’m ultimately their boss. In the beginning, I was fully authentic, expressing exactly how I feel, and that has been at times not the most well-received. So, finding the right balance, it’s a spectrum that we had to find. 

Eric: What I’d add is that in a workplace, if you’re the CEO, you do have managerial power over those you work with. So, in fact, you have to put in more work, you have even more responsibility to try and build safe spaces to receive that feedback. From a hierarchical perspective, they might not feel the same comfort sharing feedback with you that you feel with them. So, you actually have to do more work and shoulder more of a burden to try and make up for that. And again, that’s not to say we have done this super fantastic job. In fact, I think we’re still very much learning as managers. There are many things we have not done well. I say this more from a philosophical standpoint, what drives our intention, and how we think about it.

HOW TO FIND YOUR PURPOSE

I recently spoke to several Asian American high school and college students who don’t really know what they want to do with their lives and don’t really know what excites them, or how to find their passion. This seems to be a big problem among many youth, so I wanted to get Eric and Will’s perspective on what young people should be doing:

Eric: I think Will and I come from a fortunate place where we really followed those routes. Will was at Stanford, Goldman, and I was at Harvard, Blackstone. So, we have the luxury of sitting here and saying that’s really not all that it’s cracked up to be. A lot of that stuff is premised on prestige, wealth, and what other people want, and there’s a clear path on how to get there. It’s easy for me to sit here and say, forget all of that, and just do what you’re passionate about. But I’m saying this as someone who had the privilege of already going through these different experiences.

The most important thing is to feel emotionally in tune with yourself. A lot of what we do when we’re sad or frustrated leads to bad outcomes, and it’s even worse when you’re not even aware you’re sad or frustrated and that’s just fueling your actions and the choices you make. The sooner you accept that there are things you are scared about or insecure about, the sooner you’re going to be able to make decisions that are right for you. Whether that is, “Let me go work in the corporate world for x years and build up the credentials,” or “Now it’s time to leave and do something different,” 

Will: Everyone says “Be yourself” and I found that super frustrating because it’s not like  I’m masquerading as someone else. So, what goes into being yourself? I think it first comes from listening to yourself, even if you don’t trust yourself yet. Be honest about it. Even if it’s just about the prestige, go do it and do it wholeheartedly, and don’t feel any shame about it. Hopefully, that experience builds your trust in yourself. Like, “Oh, when I listened to myself and I followed my intuition, this didn’t work out so hot and that’s okay and this really worked out well so let me lean into that.” I think this is a part of the Asian upbringing. I love my parents a lot, but they didn’t know how to listen to me. They’re like, “You’re a child, I’m going to tell you what to do and you’re going to do it.” And so, I had to listen to my parents and I became my parents and I didn’t like it. In college, I had to unlearn so much of this, and Eric and I actually connected a lot over that unlearning process.

Edwin: I’m curious, I know you guys both use therapy. Has that been a big help in this journey?

Will: Eric is my therapy granddaddy, as in, I was inspired by Eric’s early experiences there and I was like, “Wow, you’re learning so much, you’re growing so much. I envy that, I want that.” I’m inspired by that and so it has been huge for my personal development and I think also my growth. So yes, it’s been crucial.

Eric: I think everyone who can afford therapy should do it. It’s unfortunate therapy is expensive but if not, I think everyone could benefit. In the same way that if you have no idea how to work out, you might have someone help teach you the ways to use your muscles. Guess what, the way you’ve lived your life, raised by your parents, surrounded by your friends and your environment, your mind has learned certain loops and ways in which it thinks. And if you want to be able to become more aware of them and try different ways of thinking, a therapist is really helpful for that.

BEING ASIAN AMERICAN

Eric: In Karat’s early days, to be honest, I wasn’t thinking about it much at all because I was focused on making the company work. Personally, I’ve only thought about it more as time has gone on and Karat’s grown bigger. Going to the Asian Hustle Network last year was super lovely because it helped me realize that I’m Asian American and that’s part of me.

Will: Eric and I used to talk about this quite a bit more in the very early days of our relationship back when we were working in corporate America. Now it’s become more about how we make the business succeed. In my lived experience, I’ve been focusing on things within my control. I really appreciated that about building a business. I just want to build something great, hire the best people, work with people I love, and serve the kind of users that I believe need the most help. That’s been exciting. 

Eric: It’s not like anything became more or less important, but in order to be an Asian American entrepreneur, you have to be an entrepreneur and your company needs to exist. There’s a certain hierarchy there of thinking about survival. 

Will: One thing that Eric and I talked a lot about in the early days was how we felt a lot of existential angst–“Is this the right thing for me?” but very little day-to-day anxiety. In the startup, it flipped. We felt a lot of day-to-day anxiety, but the existential angst vanished. That has been so freeing and so valuable that I wouldn’t want to ever go back. I wonder about the Asian American thing, perhaps that was part of the existential angst that was replaced with the day-to-day anxiety and excitement about how to make the company succeed.

SHOUTOUTS

If you are a creator looking to get a business credit card, please consider using Karat! Also, please go follow Karat on Instagram @trykarat, Eric @erictway, and Will @willikin. Thank you Eric and Will for the interview!

And finally, some parting advice from Eric: 

Advice is usually given to you from people who followed what they’re telling you now or wish they had followed what they’re telling you now. It’s not really based on you. So whenever you get advice, I’d say weigh it primarily based on the person who’s giving it, how much you actually think of yourself as similar to them or want to be them. That applies to the advice we’re giving as well.

Carl Pei-jpg

Awaken* newsletter

Quick Tips with Carl Pei

Quick Tips is a condensed version of our longer-form articles where we offer some quick one-off tips from established Asian founders. In this edition of Quick Tips, we spoke with Carl Pei, co-founder and CEO of Nothing Technology–a consumer electronics startup seeking to challenge the smartphone giants and make tech fun again.

Lots of my friends are debating whether or not to quit their jobs to start their own company. What factors would you recommend them to consider when making this decision?

It depends on whether we’re talking about a proper company or a lifestyle business. If it’s the former, remember that most startups fail, and to increase the odds of success you have to be really great at something. I recommend them to think about what they currently are, or want to be great at, and how that can be leveraged into a business. If they don’t currently possess those skills, they should think about how they can best acquire them.

You’ve mentioned that you want to make tech fun again. Why do you think consumer tech has lost its luster? Why aren’t there more companies like Nothing trying to shake things up?

Consumer tech doesn’t have a healthy ecosystem of competing companies at different lifecycle stages. When companies in this sector get big, they can protect their margins and block startups from competing for a very long time. The natural barriers to entry are already very high to making complex consumer tech products. This, coupled with technology moats and user network effects, and the entry barriers become almost insurmountable.

Steve Jobs had a famous quote: “Some people say, ‘Give the customers what they want.’ But that’s not my approach. Our job is to figure out what they’re going to want before they do.” Is this an approach you subscribe to? 

This saying is correct if the company is able to afford a risk like this, and the source of risk tolerance is free cash flow and defensibility. I believe in building a solid foundation upon which we can take risks. In practice, that means starting with giving people what they want, and gradually shifting to figure out what they’re going to want before they do.

You’ve mentioned the importance of having a creative culture at Nothing. What actions have you done to actively cultivate the culture you want at Nothing? How do you plan to scale this culture when Nothing expands as an organization?

At such an early stage, the people we choose, and the things we choose to work on defines the culture. As we expand, we don’t have to reinvent the wheel in terms of culture management strategies. We just need to tailor the tactics to the culture we intend to build.

What’s the biggest risk you’ve taken at Nothing and how did it pay off?

We haven’t taken any big risks yet; we’re still building our foundations.

Where do you see opportunities lie in Asia these days? What drew you back to Asia when you moved for the opportunity with Meizu?

They say “A rising tide lifts all boats” right? Looking ahead, if we’re talking about Asia, there should be plenty of opportunities in India and Southeast Asia. When I moved back to Asia, it was more based on a gut feeling, but in hindsight I benefited a lot being in China during the years of its fastest economic growth.

You’ve been a founder in both China and London–has your experience being an Asian founder differed in the two countries?

Not that I can think of. Different regions provide access to different types of talent, and we try to be thoughtful about where we can find the best people for the different objectives that we have to accomplish as a company.